
Denver car insurance quotes average about $112 a month for liability-only and $223 to $225 a month for full coverage, according to Compare.com and Insurify’s October 2026 data. That’s above the Colorado average. State Farm and American National often rank as the cheapest, depending on the study. Your own price depends on your ZIP code, record, credit, car, and coverage.
Averages are useful. But nobody pays an average. If you are new to the basics, see how car insurance works.
So this guide does something different. It follows one fictional Denver driver through a week of collecting quotes. Each day covers one decision. Real 2026 data sits alongside her story, so you can see where your own numbers might land.
Her name is Maya. She isn’t real. Her choices are the ones most Denver drivers face.
The Scoreboard: Denver vs. Colorado vs. the U.S.
Before Maya starts, here’s the big picture. Denver runs higher than the state average in every major study.
| Source (Updated) | Denver | Colorado | U.S. |
| Insurify (Oct. 1, 2026) | $169/month overall | $157/month | — |
| Compare.com (Oct. 1, 2026) | $168/month overall | $148/month | $143/month |
| NerdWallet (Oct. 2, 2026) | $3,885/year full coverage | $3,279/year | — |
NerdWallet’s figures show the gap clearly. Denver drivers pay about $606 more a year than the Colorado average for full coverage in its sample profile. That’s $3,885 − $3,279.
Each source uses a different sample driver. That’s why the numbers don’t match. The direction does, though. Denver costs more. Georgia car insurance quotes show the same pattern of sources that disagree on the numbers.
Meet Maya (A Fictional Example)
| Detail | Maya’s Profile |
| Age | 34 |
| Neighborhood | Capitol Hill, parks on the street |
| Car | 2021 Honda CR-V, financed |
| Record | One speeding ticket, 18 months ago |
| Credit | Good |
| Commute | About 20 minutes on I-25 |
| Current policy | Renewing in 30 days, price up 14% |
Her renewal jumped. She wants to know if that’s normal or if she can do better. Sound familiar?
Day 1: What Denver Insurance Quotes Look Like Before You Start
Maya’s first move is getting a baseline. Before she enters a single detail, she checks what Denver insurance quotes usually look like.
| Coverage Level | Insurify | Compare.com |
| Liability-only | $112/month | $112/month |
| Full coverage | $225/month | $223/month |
The two sources almost agree here. That’s rare. It gives Maya a solid range to judge her quotes against.
Her financed CR-V needs full coverage. Her lender requires it. So her target range is roughly $220 to $230 a month before her own details shift it. Lender rules work the same way elsewhere, as Arkansas car insurance quotes show.
The Colorado Rules Behind Every Quote
Denver follows Colorado’s rules. Every policy must carry at least the limits below. Commercial trucks have separate rules, covered in our guide to commercial truck insurance requirements.
- $25,000 bodily injury per person
- $50,000 bodily injury per accident
- $15,000 property damage
Two more coverages come with special rules. Insurers must offer $5,000 in MedPay unless you reject it in writing. They must also offer uninsured/underinsured motorist (UM/UIM) coverage, which you can also reject in writing. Alaska car insurance quotes show how another state handles optional coverages.
For the full statewide picture, including fault rules and penalties, our guide to Colorado auto insurance quotes and requirements covers it in detail.
What Maya Gathers
She pulls together her license number, VIN, garage address, and current declarations page. She also writes down the date of her ticket. Our guide on how to get car insurance step by step lists the full set of documents.
What Maya learned on Day 1: Two good data sources agreed within $2. That gave her a reliable benchmark before she’d asked anyone for a price.
Day 2: Setting the Coverage Before Collecting Denver Car Insurance Quotes
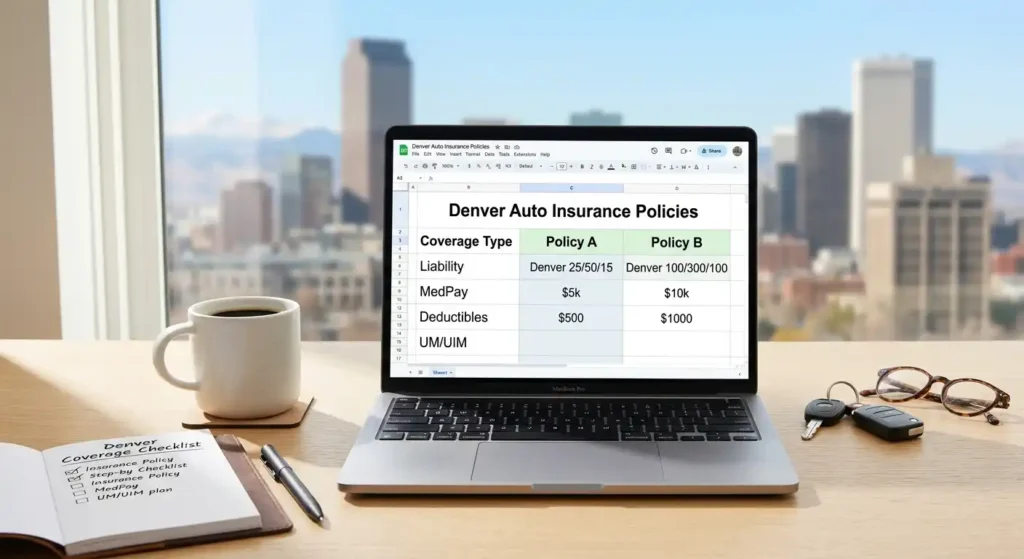
This is the step most people skip. Maya decides on her coverage before she asks for prices. Otherwise, every insurer quotes something different.
Her setup:
| Coverage | Maya’s Choice |
| Liability | 100/300/100 |
| UM/UIM | Matching 100/300 |
| MedPay | $5,000 (kept) |
| Comprehensive deductible | $500 |
| Collision deductible | $1,000 |
Why 100/300/100 instead of the state minimum? Because the $15,000 property damage minimum doesn’t go far in Denver traffic. A crash with a newer SUV can easily pass that. Our guide on how to get liability insurance and choose limits shows how limits play out in a serious crash.
Why keep UM/UIM? The Insurance Research Council estimates that 19.7% of Colorado drivers were uninsured in 2023. That ranked ninth-highest nationally. Roughly one in five drivers may have no liability coverage at all.
The Deductible Split
Notice Maya chose a lower comprehensive deductible than collision. That’s deliberate. Comprehensive covers hail and theft. Both are real risks for a car parked on a Denver street. Road damage works differently, as our guide on whether car insurance covers pothole damage explains.
Here’s the math on a hail claim with $4,500 of damage. These figures are illustrative.
- $500 comprehensive deductible: insurer pays about $4,000
- $1,000 comprehensive deductible: insurer pays about $3,500
That extra $500 matters more if you might file a hail claim every few summers. If you’d like to see how coverage choices affect cost before quoting, our car insurance calculator gives a rough estimate.
For a closer look at the coverage itself, our guide to what full coverage car insurance includes explains how comprehensive and collision split the work.
Decision checkpoint: If you park on the street, ask how much a $500 vs. $1,000 comprehensive deductible changes your price. In Denver, the cheaper deductible is sometimes worth it.
Day 3: Who Offers Cheap Car Insurance Denver Drivers Can Actually Get?
Now Maya looks for cheap car insurance Denver studies point to. She expects one clear winner. She doesn’t find one.
| Source | Cheapest Insurer Named | Rate Reported | Profile Notes |
| Insurify | State Farm | $59/month liability, $133/month full coverage | Denver sample driver |
| Compare.com | State Farm | $72/month liability | Denver sample driver |
| NerdWallet | American National | $1,609/year full coverage | 35-year-old driver |
NerdWallet also lists State Farm at $2,825 a year and GEICO at $2,836 for its sample driver.
Why the “Cheapest” Changes
Each study prices a different person. Age, credit, coverage limits, and the set of insurers included all shift the result. American National can only win in a study that includes it. Budget carriers like Direct General Insurance can also land on some lists.
What stood out to me comparing these three studies was the size of NerdWallet’s gap. American National at $1,609 a year was about $1,200 below State Farm in that profile. That’s not a rounding difference. But it was one profile. A different driver could see the order flip.
So Maya’s lesson is simple. Cheapest-insurer rankings give her a shortlist. Her own quotes give her the answer.
Maya’s Shortlist
She picks four insurers to quote:
- State Farm (cheapest in two studies)
- American National (cheapest in one)
- One regional Colorado insurer
- Her current insurer, for a renewal comparison
When you compare car insurance quotes side by side, use the exact setup from Day 2. Maya enters 100/300/100 every time.
Where to Compare Quotes
Maya has three routes for getting quotes:
| Route | Upside | Downside |
| Directly from insurers | Clean, one price at a time | Slower |
| Independent agent | Shops several insurers at once | Only insurers they represent |
| Comparison website | Fast side-by-side estimates | Follow-up calls and emails |
She uses a separate email address for quote shopping. That keeps the follow-up messages out of her main inbox.
Day 4: Testing the Best Car Insurance in Denver Beyond Price
Maya has four quotes. But price alone doesn’t tell her which is the best car insurance in Denver for her. It tells her which is the cheapest today.
So she asks a different question. What happens after a crash?
What She Checks
- Financial strength. An AM Best rating shows an insurer’s ability to pay claims.
- Complaint record. The NAIC complaint index compares complaints with company size. A score above 1.00 means more complaints than expected.
- Claims process. Online claims, local repair shops, and rental car help.
Our review of how to evaluate the best car insurance companies explains how to read these ratings.
Why Claims Service Matters More Than It Seems
Here’s the part the price tag hides. A slow or disputed claim can cost you real money. Medical bills, rental cars, and lost work days add up while you wait. If a claim turns into a dispute, our Florida insurance claim lawyer guide explains your options.
If you’re ever in a crash and want a rough sense of what an injury claim could involve, our car accident settlement calculator gives an educational estimate. It isn’t legal advice. But it shows why the insurer on the other end matters.
The Right Insurer for Different Drivers
There’s no single winner. A rough guide:
| If You Are… | Weigh This Most |
| A safe driver with good credit | Lowest price for identical coverage |
| Parking on the street | Comprehensive deductible and glass coverage |
| Financing a new car | Gap coverage and repair-shop network |
| Recently ticketed or in an accident | Size of the surcharge, not the base rate |
| Military or a veteran | Whether USAA is available to you |
What Maya learned on Day 4: Her cheapest quote came from an insurer with a higher complaint index. She didn’t rule it out. But she moved it from “obvious choice” to “maybe.” If a claim is ever denied, our Arizona insurance claim lawyer guide shows how disputes work in a neighboring state.
Day 5: Why Denver Car Insurance Rates Run High
Maya wonders why she pays more than her cousin in Grand Junction. Here’s what drives Denver car insurance rates.
Density
Denver packs about 4,674 people per square mile, compared with 56 statewide, according to Insurify. More cars in less space means more crashes. More crashes mean more claims. Commercial vehicles feel this too, as our guide to commercial truck insurance cost shows.
Theft: The Good News
Here’s the surprise. Theft is falling fast.
Insurify reports Denver ranked eighth nationally for vehicle theft per capita in the first half of 2025, with 6,116 thefts. That was a 33% drop from 2024. And the Colorado State Patrol reported in March 2026 that statewide thefts have fallen more than 55% since 2021. Colorado moved from the worst state for auto theft to 14th.
Why haven’t premiums dropped to match? Insurance pricing lags behind claim trends. Insurers set rates using several years of data. So, the improvements may show up in prices slowly, if at all. That’s worth watching at your next renewal. Business coverage follows the same lag, as our guide to general liability insurance cost for an LLC explains.
Hail
Colorado sees frequent severe summer storms. Hail falls under comprehensive coverage. That’s one reason full coverage costs about twice as much as liability in Denver. Home policies face the same hail risk, as our guide to home insurance quotes in Rhode Island explains.
Uninsured Drivers
With roughly one in five Colorado drivers uninsured, insured drivers absorb part of that cost through UM/UIM and claims. For a broader look at how insurers price these risks, our guide to what drives car insurance costs explains the logic.
Day 6: The Record Check
Maya’s ticket is 18 months old. She wonders how much it’s costing her. Compare.com’s October 2026 Denver data shows how violations change the average.
| Record | Average Monthly Rate | Increase vs. Average |
| Average Denver driver | $168 | — |
| One speeding ticket | $217 | +$49 |
| One at-fault accident | $225 | +$57 |
| One DUI | $234 | +$66 |
| Poor credit | $210 | +$42 |
These are averages across different sample profiles, not a single driver. But the pattern is clear.
Here’s what a ticket means over time. This is illustrative.
- Extra cost: $49 a month × 12 = $588 a year
- If it affects rates for three years: $1,764
That’s far more than the ticket itself. Many violations affect rates for three to five years. Maya marks her calendar. Her ticket may stop counting at a future renewal.
If Your Record Is Worse
Surcharges vary widely by insurer. One company may barely react to a ticket. Another may raise rates sharply. Our guide to the cheapest high-risk car insurance companies shows how much prices vary after a violation.
A DUI often brings an SR-22 filing too. Insurers usually charge a small fee to file it. The higher cost is the premium increase. Our review of the best SR22 insurance companies explains how those filings work in Colorado and elsewhere.
Day 7: Maya’s Decision
Maya lines up her four quotes. These figures are illustrative, not real offers.
| Insurer | Monthly Price | Same Coverage? | Complaint Index | Notes |
| Quote A | $198 | Yes | Above 1.00 | Cheapest |
| Quote B | $209 | Yes | Below 1.00 | Strong claims reviews |
| Quote C | $214 | Yes | Below 1.00 | Regional insurer |
| Current insurer | $246 | Yes | Below 1.00 | Her renewal price |
She picks Quote B. It costs $11 more a month than Quote A, or $132 a year. She decides that’s a fair price for a better complaint record.
Compared with her renewal, she still saves $37 a month, or $444 a year. Bundling home and auto insurance could add more savings later.
The Discounts She Almost Missed
Before signing, Maya asks about discounts. Paperless billing and paying in full shave off a bit more. Our guide to car insurance discounts and how they stack explains why several small discounts rarely add up in a straight line.
She also rents, so she asks about bundling renters insurance. Options like USAA renters insurance show how renter bundles work for eligible drivers.
If you own a home, bundling home and auto can matter more. Our walkthrough of an Allstate homeowners quote shows how advertised bundle savings compare with typical ones.
The Friction Point
Here’s what nearly tripped her up. The new policy showed a slightly higher price at checkout than the online quote. Why? The insurer pulled her motor vehicle record and found the ticket she’d listed with the wrong month. She corrected it. The price adjusted back.
The lesson: enter your history accurately. And don’t cancel your old policy until the new one is active.
If You’re Not Maya: Four Other Denver Profiles
Your quotes may look very different. Compare.com’s October 2026 Denver averages show the spread. Business owners should also read whether an LLC needs commercial insurance.
The Teen Driver
Teens in Denver average about $308 a month, according to Compare.com. Adding a teen to a parent’s policy is usually cheaper than a separate policy. Good student discounts can help.
The Senior Driver
Seniors average about $136 a month, well below the city average. Mature-driver course discounts may lower it further. Retirees who travel may also want RV insurance quotes in Florida.
The Driver With Poor Credit
Colorado allows credit-based insurance scores. Compare.com puts poor-credit drivers at about $210 a month. Improving credit can lower your price at renewal.
The Gig Driver
Delivering food or driving rideshare in Denver? A personal policy may not cover that use without an endorsement. Our guide on when commercial auto insurance is needed explains when personal coverage stops applying.
When the Expensive Option May Not Pay Off
Say you own a paid-off 2010 sedan worth about $4,000. Full coverage costs roughly 113amonthmorethanliabilityinDenver,usingInsurify’saverages(225 − $112). That’s about $1,356 a year. With a $1,000 deductible, a total loss would pay about $3,000 at most. In a little over two years, you’d pay more in extra premium than the car could pay out. For a car like that, liability-only plus UM/UIM may be the more practical setup. Work trucks follow different math, as our guide to cheap commercial truck insurance shows.
Your Quote Checklist
Maya’s week shows the pattern. Denver car insurance quotes vary by insurer, profile, and coverage. The studies give you a range. Your own quotes give you the answer.
Before you buy:
- [ ] Set your coverage first, then quote
- [ ] Keep MedPay and UM/UIM consistent across quotes
- [ ] Choose a comprehensive deductible you could pay after a hailstorm
- [ ] Quote at least one national and one regional insurer
- [ ] Check complaint records, not just price
- [ ] Enter your driving history accurately
- [ ] Start the new policy before canceling the old one
Here’s one practical next step. Write down your Day 2 setup tonight. Then collect quotes from three or four insurers using that exact setup. If one price looks far lower, check whether it quietly dropped coverage.
Reader Questions
Is car insurance in Denver more expensive than in the rest of Colorado?
Yes. Compare.com puts Denver at $168 a month on average, versus $148 statewide. NerdWallet’s full-coverage figures show a gap of about $606 a year.
Which insurer is cheapest in Denver?
There’s no single answer. In October 2026 studies, State Farm ranked cheapest for Insurify and Compare.com, while American National led NerdWallet’s profile. Quote both, plus a regional insurer.
How many quotes should I get?
At least three. Use identical limits and deductibles on each. Include at least one regional insurer.
Which Denver insurer is best?
It depends on your profile. The best choice usually combines a competitive price with a solid complaint record and financial strength. Check both before buying.
Does getting a quote affect my credit?
Insurance quotes generally use a soft credit check, which doesn’t affect your credit score. Ask the insurer if you’re unsure.
Will falling car thefts lower my rate?
Maybe, but slowly. Colorado thefts have dropped sharply since 2021. Insurers price using several years of data, so savings may take time to appear.

Michael Bennett is a U.S. insurance research and consumer education writer at Insurancebasics Hub, an independent resource dedicated to helping consumers understand insurance policies, coverage decisions, claims, and insurance-related consumer protections. His work covers auto, homeowners, renters, life, and other areas of insurance, with a focus on making complex insurance topics easier to understand.
Michael takes a research-focused approach to insurance content, using authoritative government and regulatory resources, state insurance department guidance, applicable insurance rules, policy provisions, and documented industry information. His articles examine important details such as coverage limits, deductibles, exclusions, policy conditions, premiums, claims, denials, cancellations, renewals, and state-specific requirements.
His goal is to provide accurate, transparent, and practical information that helps readers make better-informed insurance decisions. Insurancebasics Hub provides general educational information and does not replace individualized advice from a licensed insurance professional, attorney, financial professional, or other qualified adviser.